

Motor, home and commercial. Reasons on every claim.
Your volume lines already run on models: triage scores, reserve suggestions, fraud flags and renewal prices. HONESTAS keeps the part of the file that usually goes missing: who decided, on what evidence, under which wording and which authority. From first notice of loss to a sealed settlement.


Six decisions in every claims and pricing book.
Each one leaves the same kind of record. Open one to see what goes in, what comes out and who signs.


First notice of loss and triage
The claim opens from the call, the app, the web form or an email. Cover is checked, and triage sends it to the right queue, or to a decision room with a named chair when the amount or the signals call for one.
- Goes in
- Calls, forms, emails, photos and the policy
- Comes out
- An open claim with cover checked, a route and a list of what is still needed
- Signs
- Claims handler
Reserves and payments on account
AI suggests a reserve with the papers behind it. A payment on account goes out with its own reason and its own record, so a part payment never reads like a final offer.
- Goes in
- The adjuster's report, estimates and claims history
- Comes out
- A reserve with its basis, and each payment with its reason
- Signs
- Claims handler within authority. A second person above your limit
Settlement, betterment and declines
The decision room argues for and against paying. A betterment deduction or a decline carries the clause that decides it, in words the customer can read.
- Goes in
- The claim file, the wording and the points in dispute
- Comes out
- A ruling with reasons, and a drafted decision letter
- Signs
- The chair, usually the claims lead
Subrogation and recoveries
When someone else is to blame, the recovery file is built from the same sealed record, with the evidence the other side will ask for and the payments made.
- Goes in
- The sealed decision, liability evidence and payments
- Comes out
- A recovery file and a drafted demand
- Signs
- Recoveries handler
Complaints
A complaint opens on the record it is about. The handler sees the decision, its reasons and what the customer was told, and the reply is checked before it leaves.
- Goes in
- The complaint, the sealed decision and the letters sent
- Comes out
- A reply with the facts it rests on, inside your response deadline
- Signs
- Complaints handler
Renewals and pricing
A rate table change shows every price it moves before anyone approves it. Each motor and home renewal price is checked against the ceiling the pricing rules set: an equivalent first-year renewal in Ireland, an equivalent new customer in the UK.
- Goes in
- The rating model, rate tables and the renewal book
- Comes out
- Approved tables, and a check on every renewal price
- Signs
- Pricing actuary, then a second approver
A storm, a cold store and a £1.24m claim.
A commercial property claim at Northgate Mutual, a fictional insurer. Six steps, from the first call to a sealed settlement the reinsurer can check. Scroll, and the screen follows the step.
- 01 · First notice
Storm Ashling takes the roof off a cold store.
Rita Okon at Harbourline Cold Store rings on 2 October. The claim opens from the call, cover is checked under the commercial property wording, and triage sends it to a decision room because of its size.
Rita Okon reports it. The claims desk checks the summary.
honestas · claims · CLM-7741Sample dataClaim 7741 · Storm damage to a cold store roofCLM-7741NewFirst noticePayment on accountEvidenceRoomAuthoritySealedFrom the call- Insured
- Harbourline Cold Store
- Caller
- Rita Okon
- Event
- Storm Ashling · 2 Oct
- Broker
- Tollard
Cover check- Section
- Buildings, storm
- Also
- Business interruption
- Excess
- £250,000
- Status
- Covered so far
TriageFirst estimate is above £500,000, so the claim goes to a decision room with Sara Lindqvist, claims lead, in the chair.
Opened from the call transcript. Nothing was decided.
- 02 · Payment on account
Money moves before the claim is settled.
The store needs to keep its stock cold. On 9 October Sara agrees a payment on account of £310,000. It carries its own reason, tells the customer it is not a final offer, and is sealed as its own record.
Sara Lindqvist, claims lead, asks for it. A second person agrees it.
honestas · claims · claim paymentsSample dataPayment on account · CLM-7741CLM-7741Paid 9 OctFirst noticePayment on accountEvidenceRoomAuthoritySealedThe payment- Amount
- £310,000
- To
- Harbourline Cold Store
- Why now
- Stock must stay cold
- Asked by
- Sara Lindqvist
What the customer will seeWe have paid £310,000 on account so you can keep trading. This is not our final offer. We will write again once the adjuster has reported.
record 2026-1009-7741 decided Payment on account · £310,000 sealed 9 Oct 2026, 14:02 BSTSealed as its own record, separate from the settlement - 03 · Evidence
Every paper, with its source and its age.
The adjuster's report, fourteen photos, the customer's estimate and the claims history are gathered in the evidence tray. Each item shows where it came from and whether it is still fresh enough to rely on.
Sara reads the tray before the room sits.
honestas · decision evidence · the evidence traySample data

The evidence tray. Nine items, each with where it came from and how old it is against its limit. What is missing is typed, not left blank.Sample data - 04 · Decision room
Pay in full, or deduct for betterment?
One AI seat argues for paying in full. One argues for a betterment deduction. The challenger raises the 2023 roof and its fitter, now in administration. Sara rules to pay in full and opens a recovery.
Sara Lindqvist chairs. The second model agrees with her ruling.
honestas · decision rooms · CLM-7741Sample dataSettlement · Claim 7741CLM-7741Chair to ruleFirst noticePayment on accountEvidenceRoomAuthoritySealedChairSara LindqvistClaims leadAI · forPay in fullStorm, photos, reportAI · againstBettermentNew panels, higher specChallengerThe 2023 roofFitter now insolventCase againstThe new panels are a higher specification than the old roof. Part of the cost may be betterment.ChallengerThe roof was fitted in 2023 by a firm now in administration. Its guarantee may cover part of this. Ask before paying in full.Sara LindqvistPay in full, £930,000 more. The old panels are no longer made, so like for like is not possible. Ask the administrators for the 2023 guarantee and open a recovery.Second model: agrees with the ruling. Nothing goes out until both agree.
- 05 · Authority
Checked before she signs.
HONESTAS works out what this act commits against her authority for Storm Ashling claims. Every check passes, so she can sign. Had it failed, the claim would have gone to the person named in the referral rule.
Priya Raman recorded the power. She cannot use it herself.
honestas · decision evidence · allowed to decide it?Sample data

Is she allowed to decide it? Sara may commit £930,000 more on Storm Ashling claims and stay inside her £5,000,000 limit. Nine checks, in order, before anyone signs.Sample data - 06 · Sealed
Signed, sealed and sent to the reinsurer.
Sara signs with her passkey. Both decisions travel as one Decision Passport, sent to the reinsurer with a link that expires. Anyone with the link can check it, with no account.
Kelling Reed, the reinsurer on the layer, checks it from their side.
honestas · decision evidence · passportSample data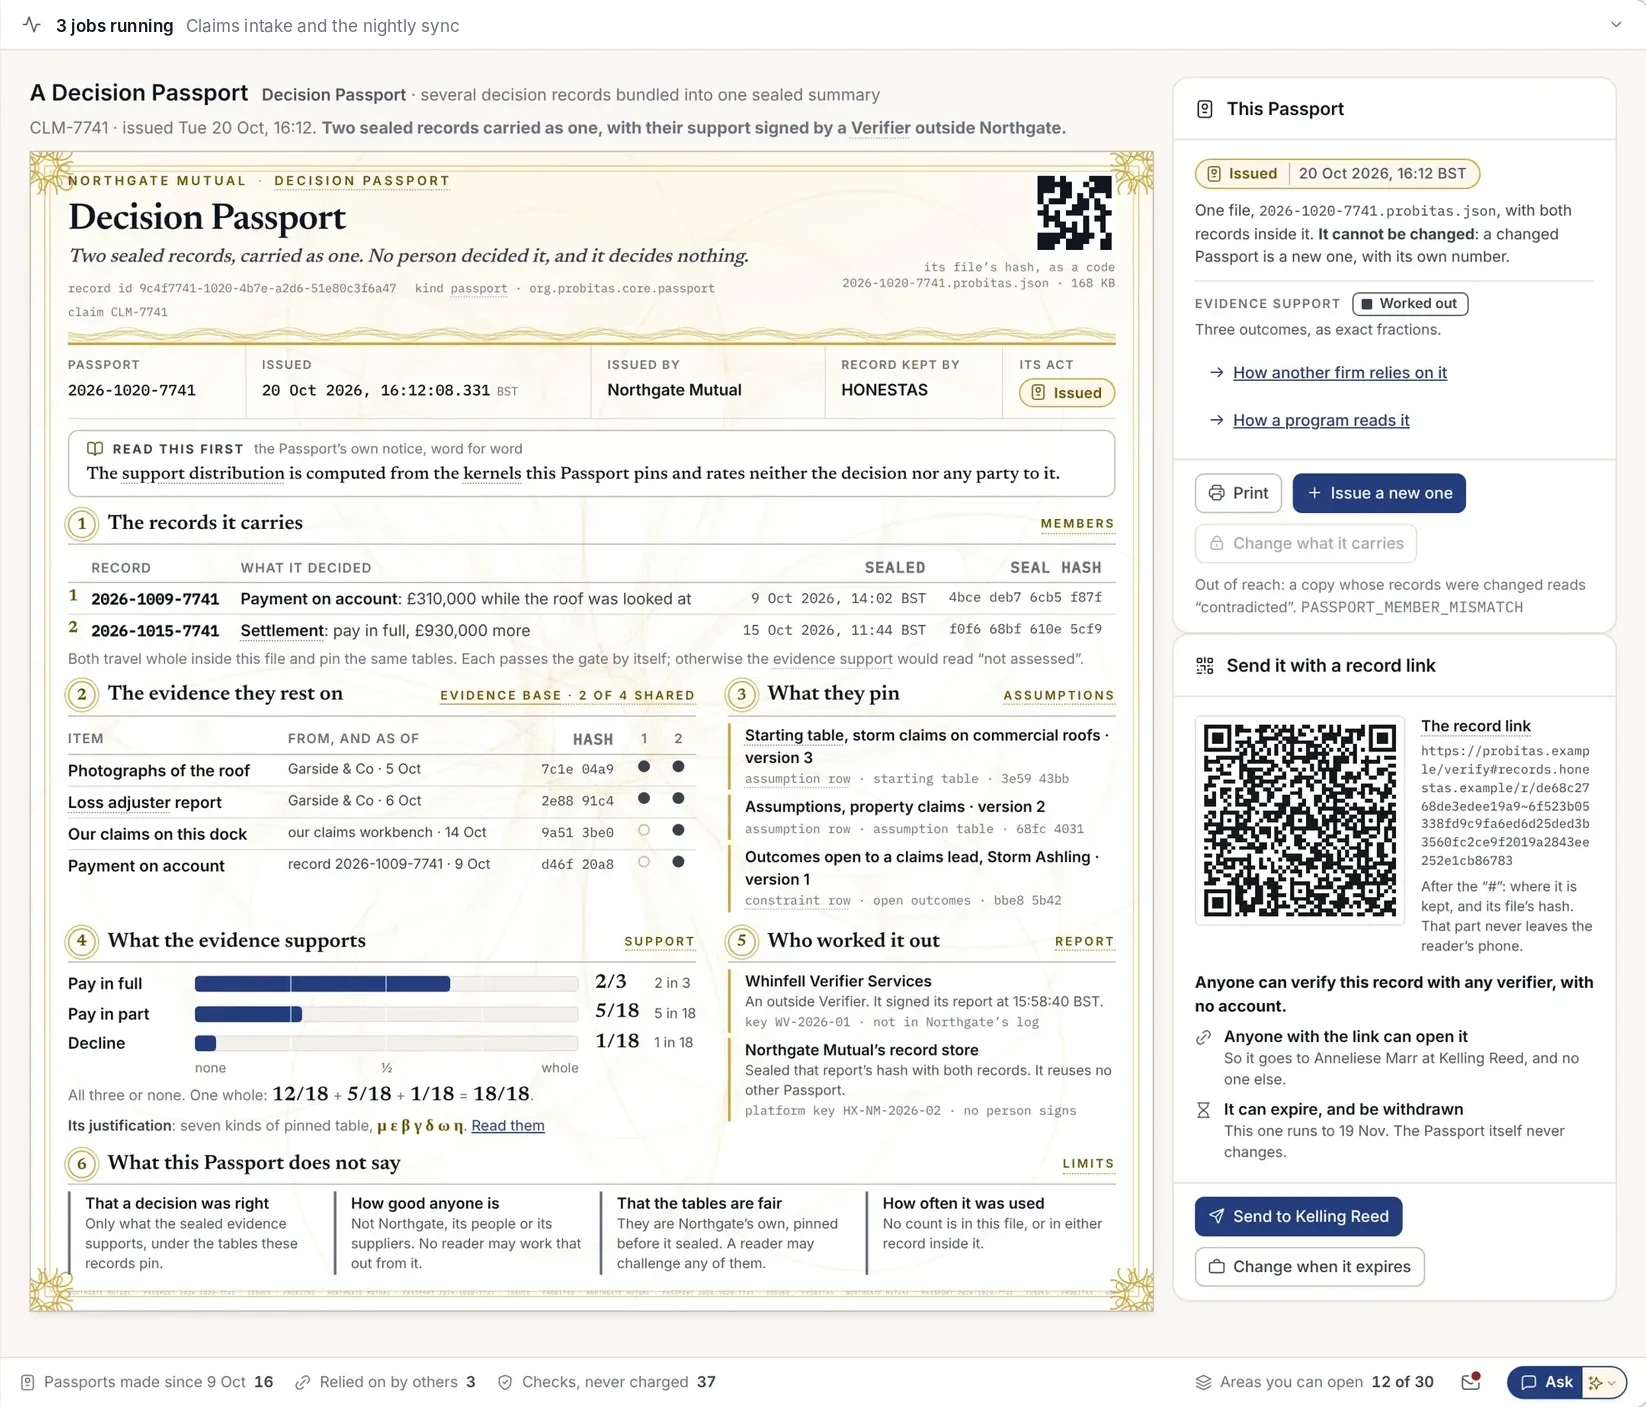
Two decisions, one Passport. The payment on account and the settlement, with the evidence they rest on and what the Passport does not say.Sample data
- Insured
- Harbourline Cold Store
- Caller
- Rita Okon
- Event
- Storm Ashling · 2 Oct
- Broker
- Tollard
- Section
- Buildings, storm
- Also
- Business interruption
- Excess
- £250,000
- Status
- Covered so far
First estimate is above £500,000, so the claim goes to a decision room with Sara Lindqvist, claims lead, in the chair.
Opened from the call transcript. Nothing was decided.
- Amount
- £310,000
- To
- Harbourline Cold Store
- Why now
- Stock must stay cold
- Asked by
- Sara Lindqvist
We have paid £310,000 on account so you can keep trading. This is not our final offer. We will write again once the adjuster has reported.
Second model: agrees with the ruling. Nothing goes out until both agree.
Mapped to the rules for motor, home and commercial.
Each sealed record is linked to the articles it helps answer, so the evidence is ready before a supervisor asks.
- Solvency IIDirective 2009/138/EC, as amended by (EU) 2025/2Governance, risk management and reserves you can explain. The reviewed rules apply from 30 January 2027.
- Insurance DistributionDirective (EU) 2016/97 (IDD), Art 17 and 25Act honestly, fairly and in the customer's best interests, with product oversight for every product you sell.
- DORARegulation (EU) 2022/2554ICT risk, incident reporting and the register of ICT suppliers, applying since 17 January 2025.
- GDPRRegulation (EU) 2016/679, Art 22A claimant may ask for a person to review a decision made only by automated means. In HONESTAS a named person signs every one.
- Consumer Protection CodeCentral Bank of Ireland, S.I. 80/2025 and 81/2025Clear information and fair treatment for customers in Ireland, applying from 24 March 2026.
- Price walking, IrelandInsurance Requirements Regulations 2022No motor or home renewal priced above the equivalent first renewal price, and a yearly review of pricing. Since 1 July 2022.
- Pricing practices, UKFCA ICOBS 6B (PS21/5)A home or motor renewal price no higher than the equivalent new business price. Since 1 January 2022.
- Consumer Duty and claims, UKFCA PRIN 2A and ICOBS 8.1.1RGood outcomes and fair value for retail customers since 31 July 2023, and claims handled promptly and fairly.
Not legal advice. Certification and legal opinions stay between you and your advisers.
Go deeper
See it on your own claims.
Bring one claim type, such as motor glass, escape of water or a commercial storm loss. We will run it from first notice to a sealed settlement.