

Ready before the storm makes landfall.
HONESTAS puts every insured property on one map beside live hazard feeds. Before an event you see the exposure in its path. When it lands, the decisions it forces, from a binding restriction to extra claims authority, are argued, signed and sealed as fast as the claims arrive.
The biggest Irish windstorm loss in at least 45 years.
Windstorm Éowyn crossed Ireland and the UK on 24 and 25 January 2025. The market's estimate of the loss kept moving for a year afterwards. Insurers still had to decide in the first days what to pay, whom to send and what to reserve.
Source: PERILS, final industry loss estimate for Windstorm Éowyn, 26 January 2026. Property lines.
Know the exposure first. Decide the rest on the record.
Before the season, during the event and long after it, the exposure, the claims and the decisions sit in one place.
Exposure before the season
Every insured property is on the map, with sums insured added up by county, postcode and treaty, and set against your reinsurance limits.
Track the event
Live hazard feeds show the storm's path. Draw the footprint and see the policies and sums insured inside it, and the claims that are likely to come.
Decide what it forces
Binding restrictions, event authority, payments on account and loss adjusters are each argued in a room and signed by a named person, the same day.


Sealed for the recovery
Every event decision and claim is tied to the event and sealed. Your reinsurer reads the event record as one file it can check, with no account.


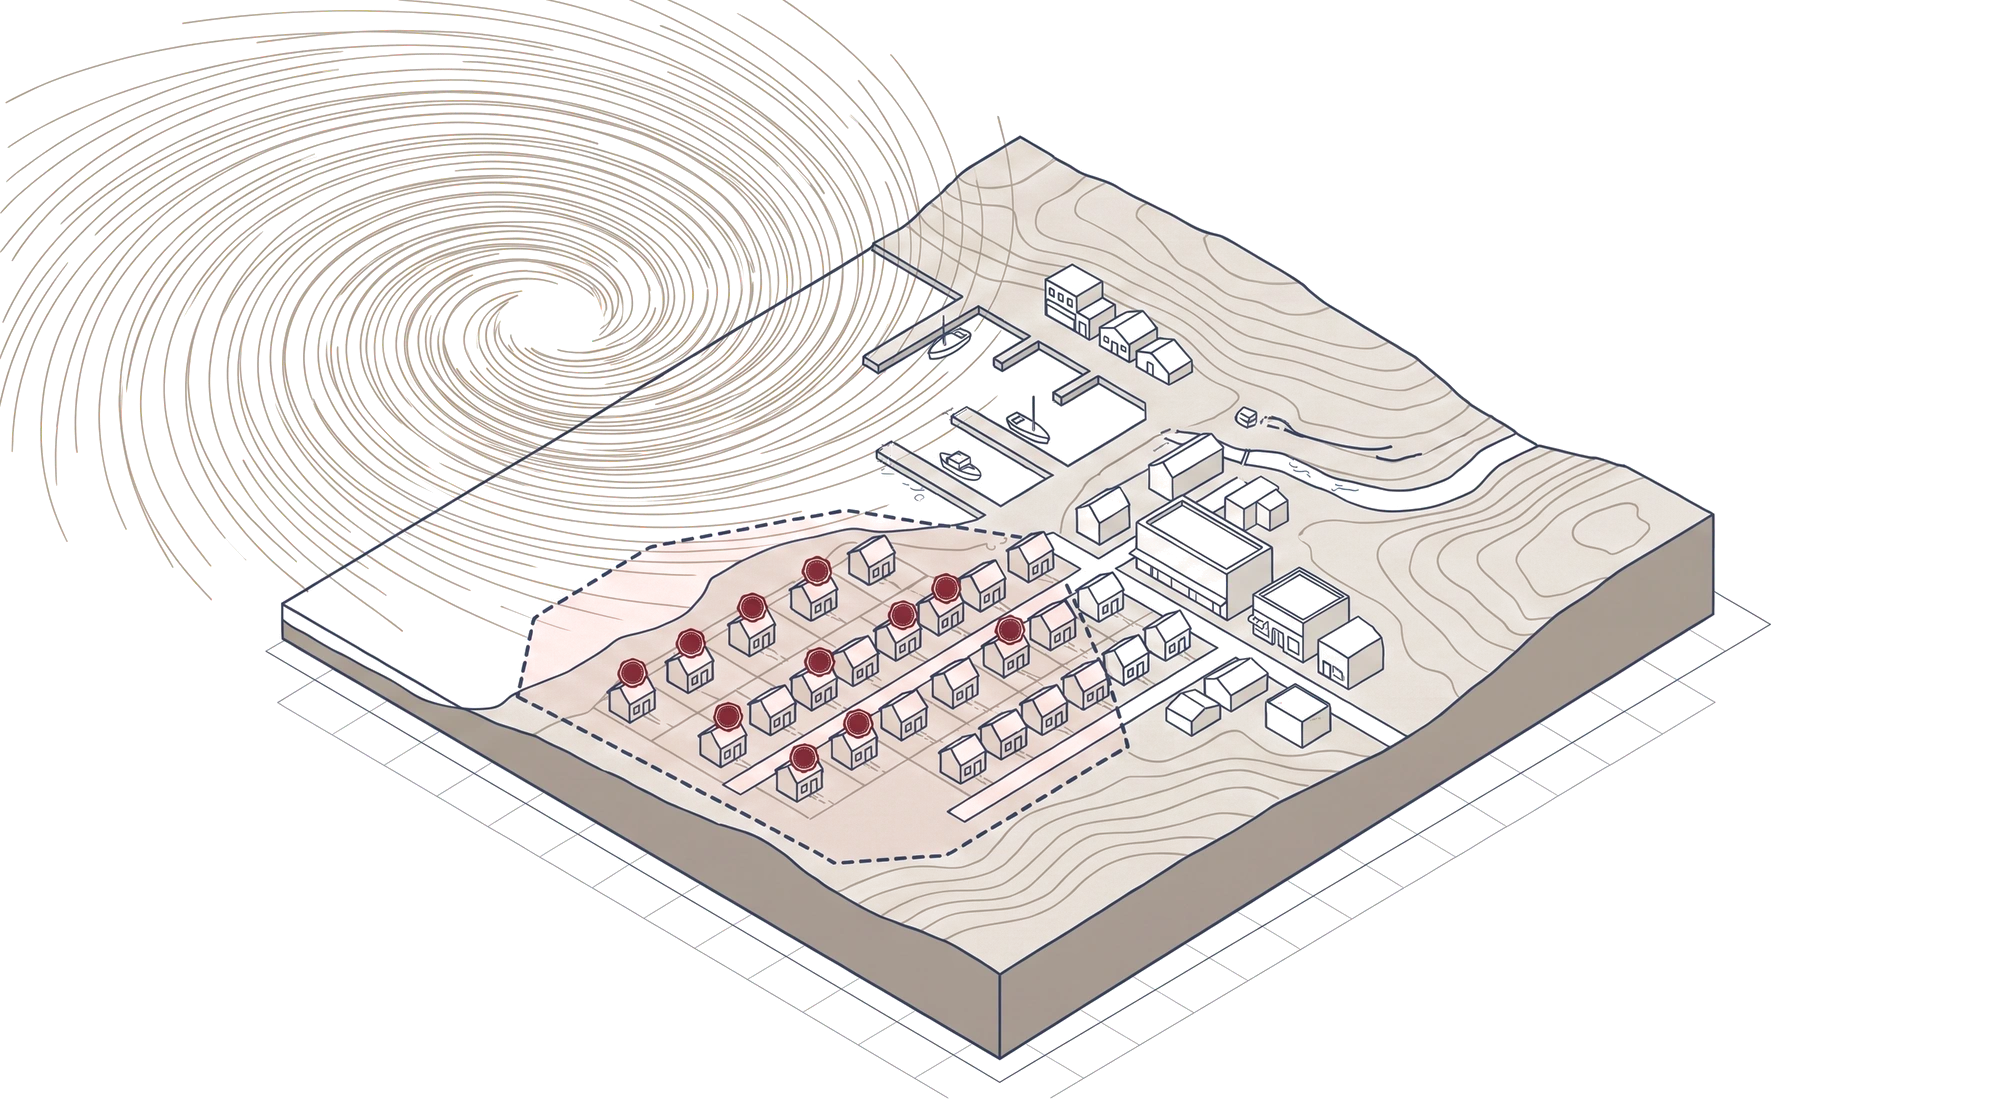
Six decisions in the first days. Each one signed.
An event does not wait for a quiet week. HONESTAS opens a room for each decision it forces, with the right chair and the exposure in front of them, and seals what they decide.
- Binding restriction
No new business or changes to cover in the path, from a stated time, signed by the head of underwriting.
- Event authority
Extra claims authority for named handlers, for this event only, with an end date.
- Payments on account
Emergency payments for repairs and alternative accommodation, each with its reason.
- Loss adjusters
Who goes where first, sorted by the exposure in each area.
- Event reserve
The first reserve for the event and each change to it, with the estimate it rested on.
- Reinsurance notice
Notice to the catastrophe treaty, with the event record attached.
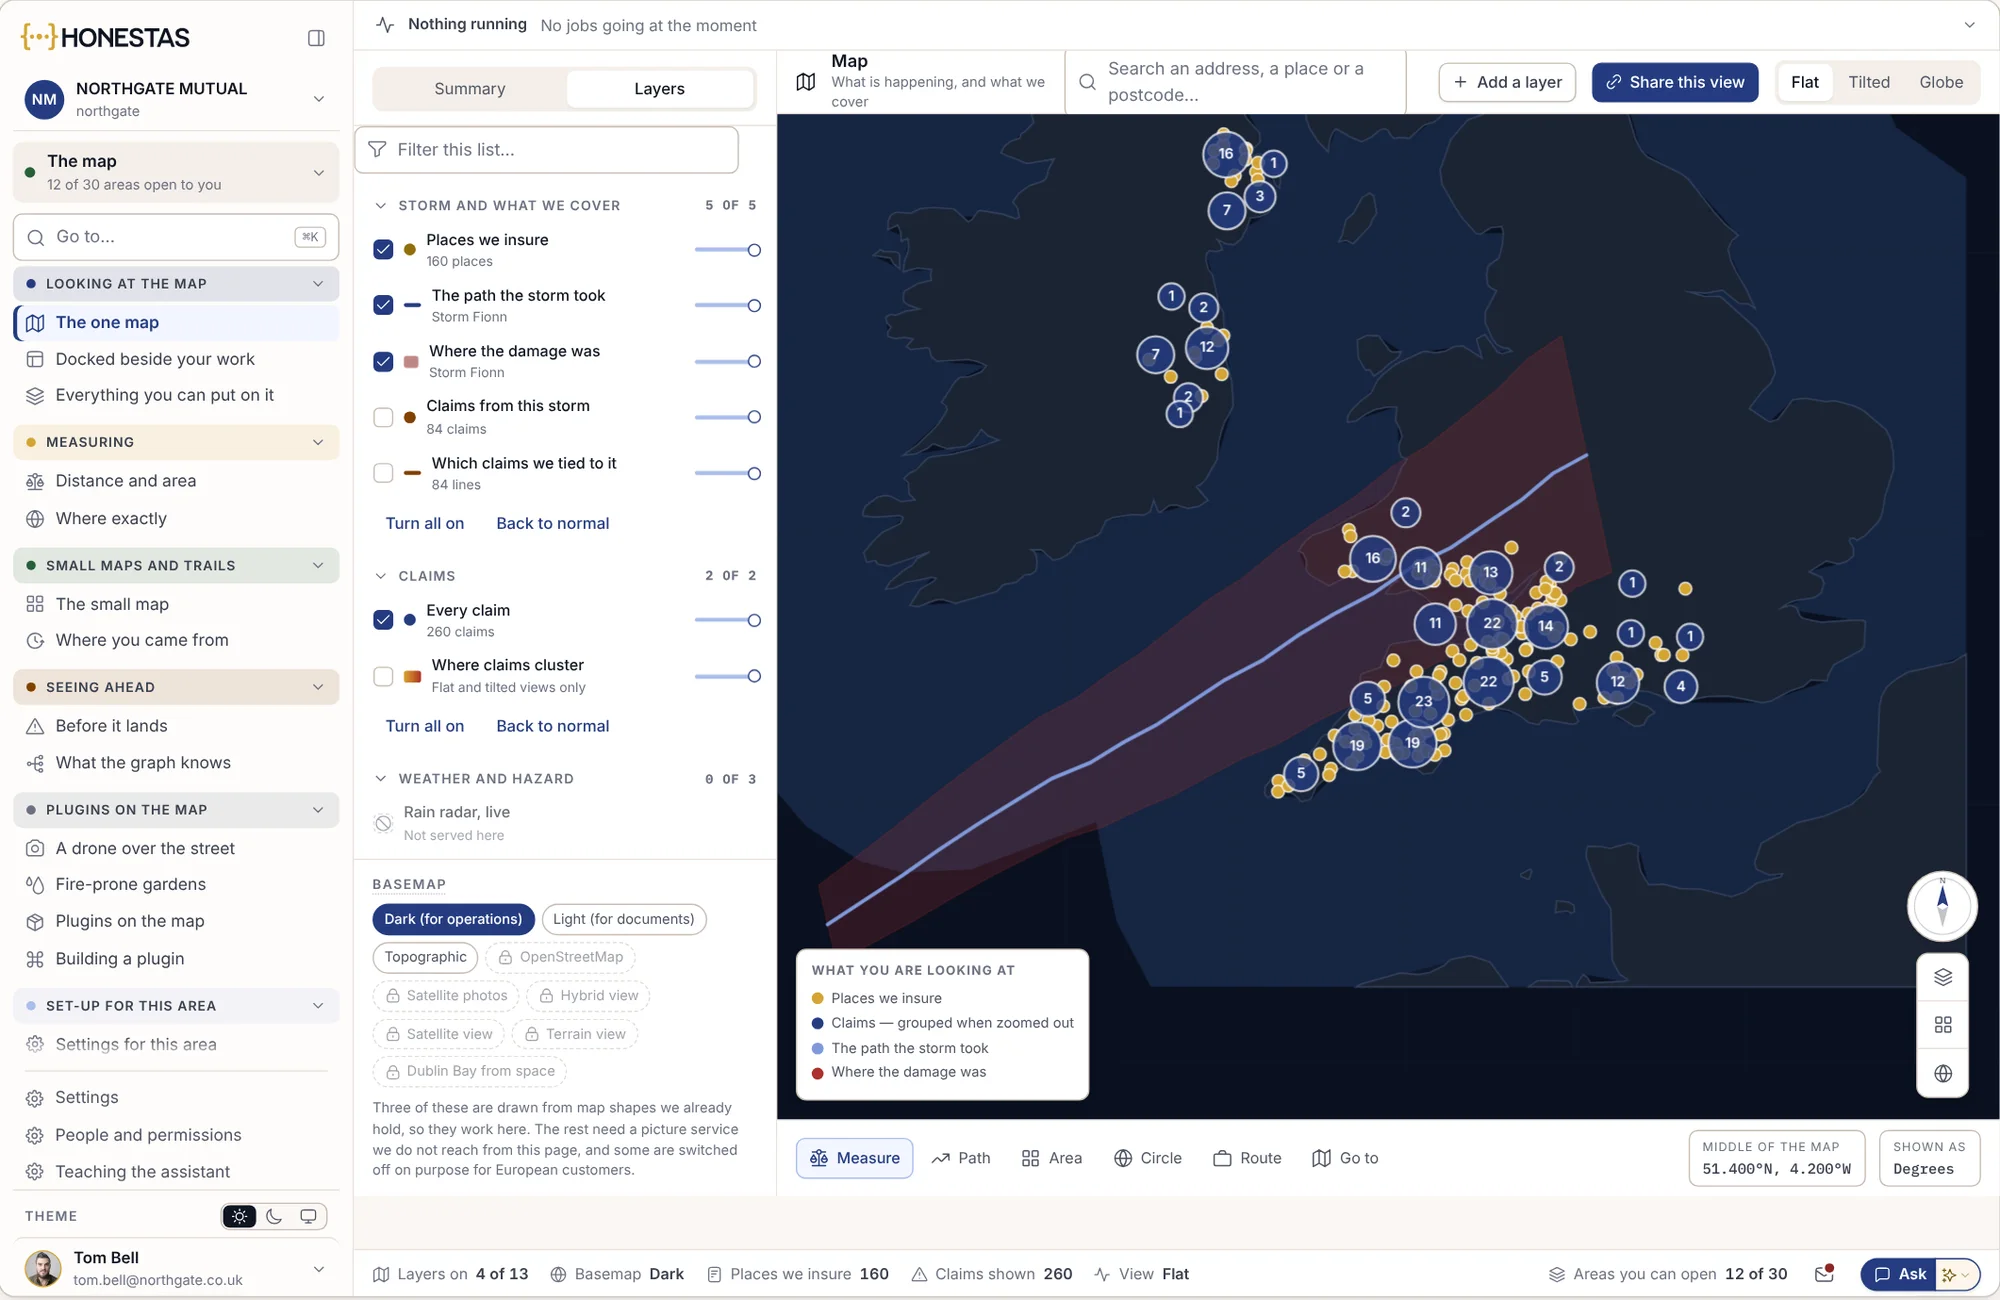
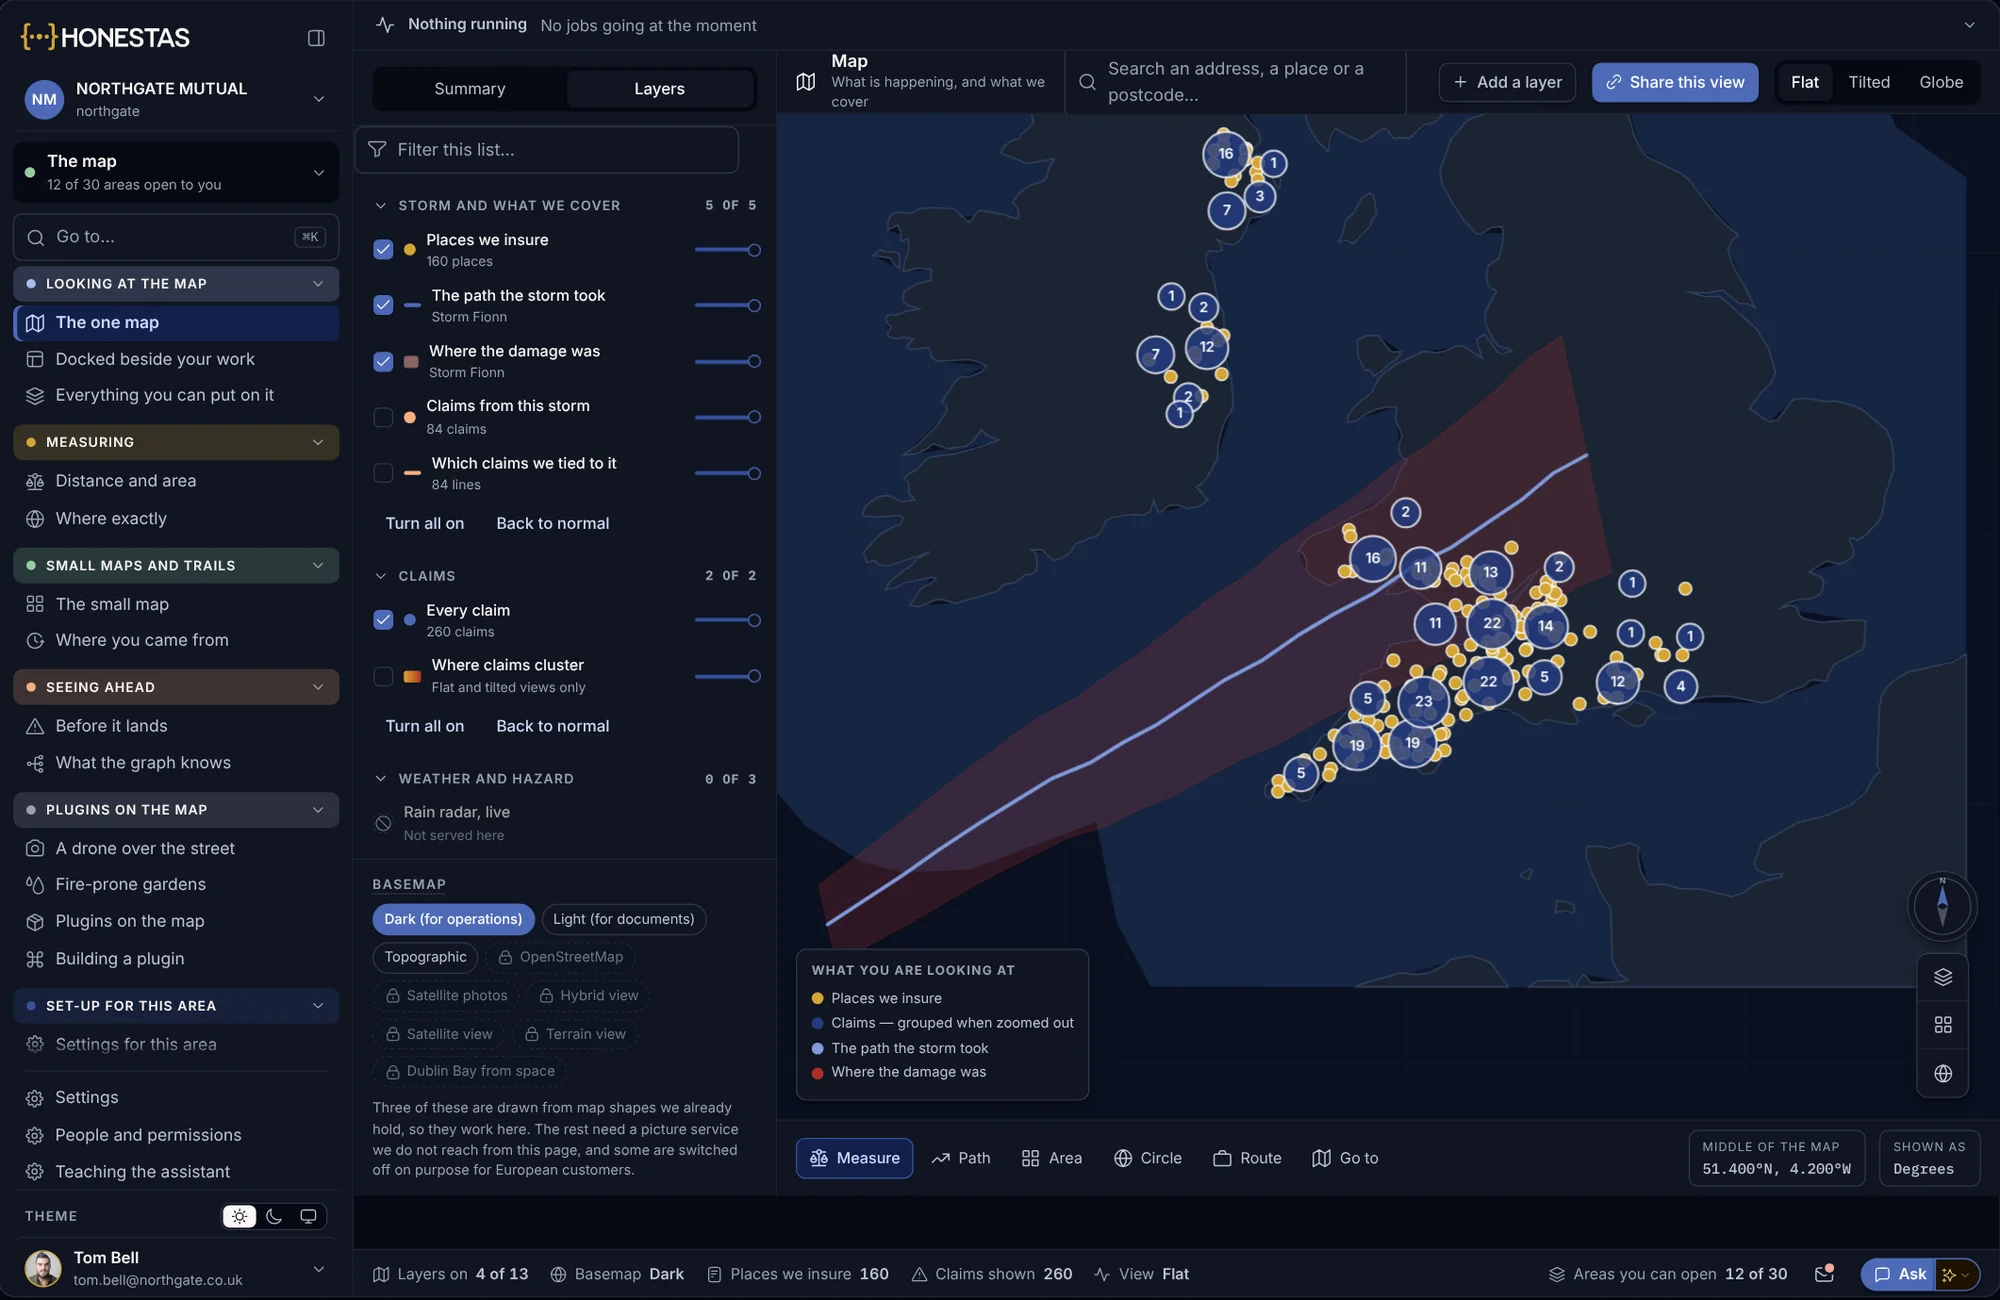
The storm, the book and the claims on one map.
These are HONESTAS screens, shown with sample data from Northgate Mutual, a sample organisation.
Exposure, path and claims together
The places you insure, the path the storm took, where the damage was and the claims that came in, as layers on one map.
- Each layer switched on or off
- Claims grouped as you zoom out
- The view shared as a link
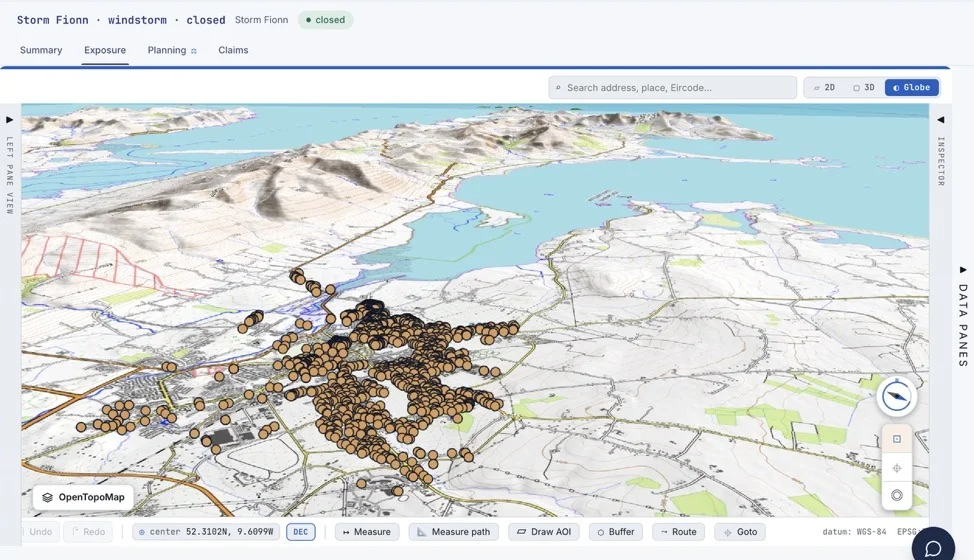
Every property on the ground
The insured properties under a storm, on a 3D map of the land around them, with tools to measure, draw an area and add a buffer.
- Flat, 3D or globe
- Draw an area or a buffer
- Exposure, planning and claims views
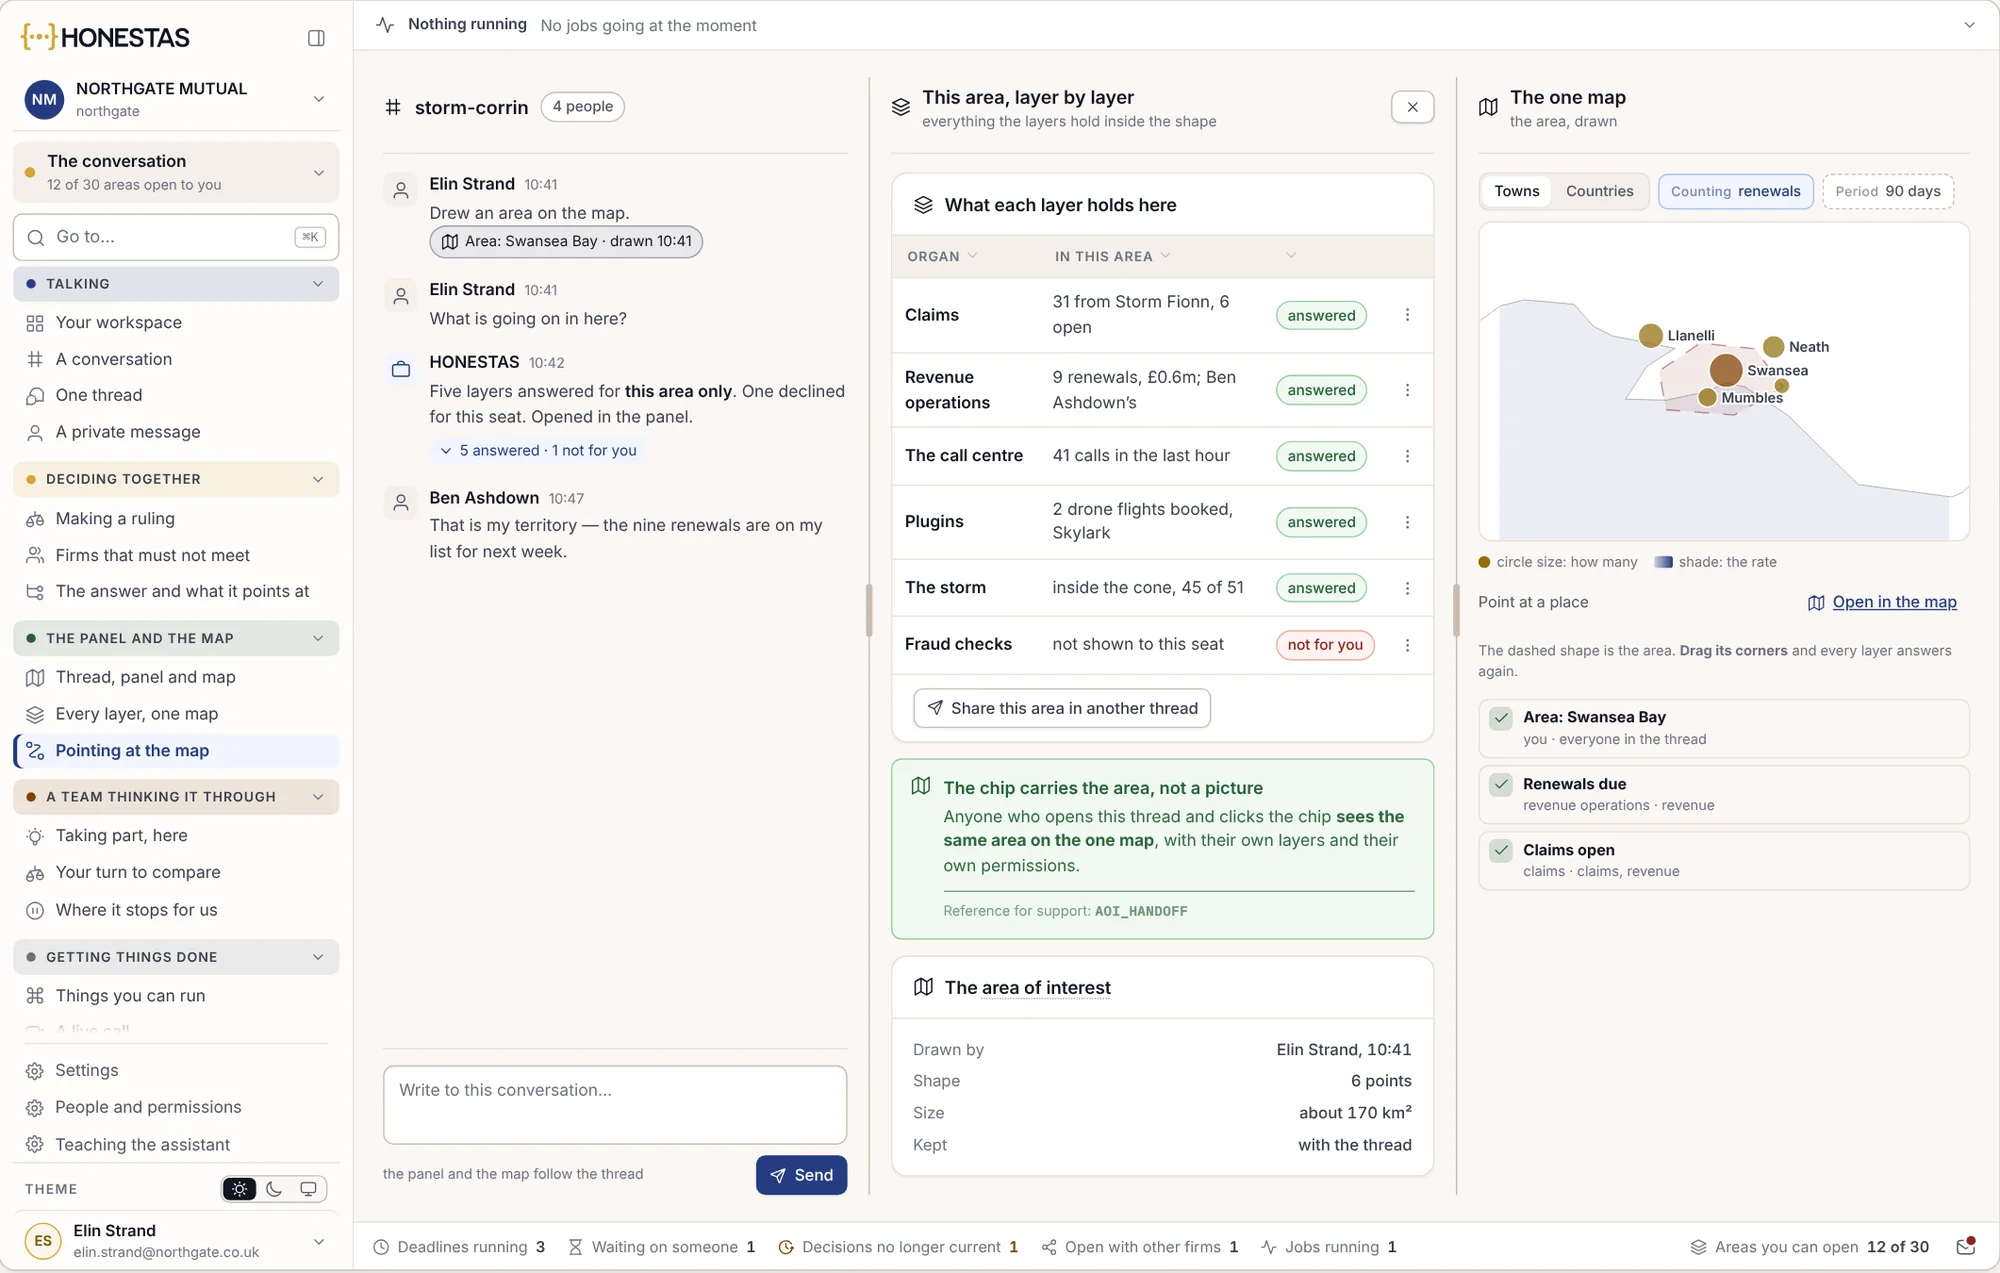
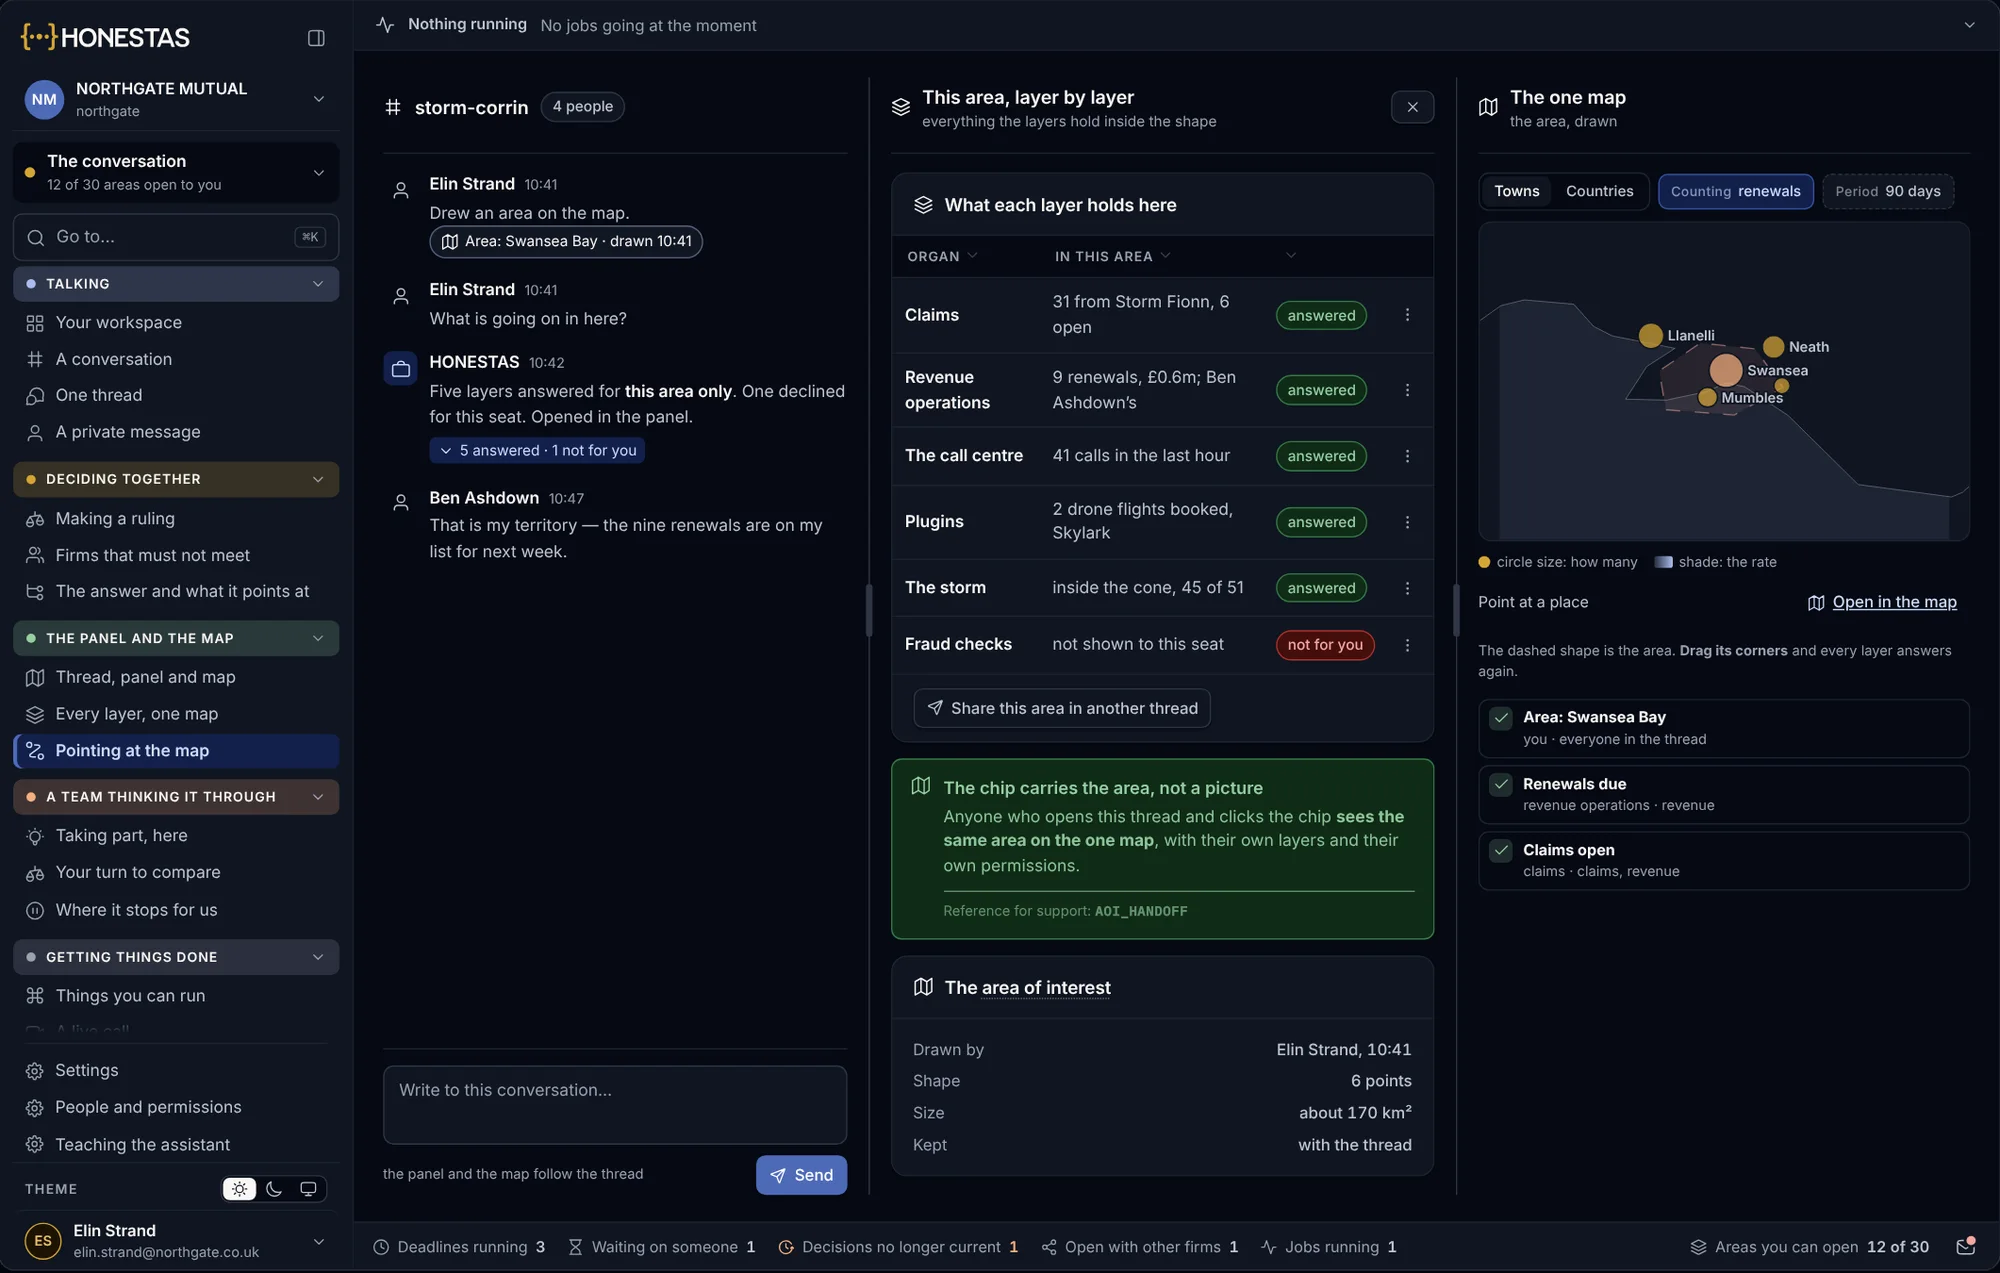
Ask about one area
Draw an area in a conversation and every layer answers for that area only: claims, renewals, calls and the storm. A layer you may not see says so.
- The area travels with the thread
- Each layer answers within your permissions
- Drag a corner and it answers again
Measure the first days, then the recovery.
These are the measures a head of catastrophe or claims tracks through an event, read from the sealed exposure views, decisions and claims.
- Exposure in the path
- Policies and sums insured inside the footprint, and how soon after the first warning you knew.
- Restriction time
- Time from the first warning to a signed binding restriction.
- Claims notified
- Event claims notified each day, against those triaged to a chair.
- First payment
- Days from notification to the first emergency payment on account.
- Event reserve
- Each movement in the event reserve, against the market's loss estimates.
- Signed decisions
- The share of event decisions argued, signed and sealed rather than taken by email.
- Recovery
- Days from notice to the reinsurer to settled recovery, and the questions it asked.
Catastrophe readiness, in practice.
Which hazard feeds does the map use?
Copernicus, NOAA, USGS and FIRMS, live, beside your own exposure data and any feed you already license.
Does HONESTAS replace our catastrophe model?
No. Your catastrophe models keep producing the numbers. HONESTAS reads their output, puts it on the map and keeps it with the decisions that relied on it.
Can we rehearse an event before the season?
Yes. Run a past or imagined storm through the book in stress testing, and open the rooms it would force, without touching live policies.
What does the reinsurer see?
A Decision Passport for the event: the sealed decisions, the exposure views they used and the claims tied to the event. They check it with no account.
Go deeper
Bring last winter's storm.
We will run it through a sample book and show you the exposure, the rooms it would open and the record your reinsurer would read.